I have to admit, burnt orange isn’t usually my jam, but I fell in love with the tones in the photo of the spices, and had to roll with it! I think this mood board would translate into a stunning real-life situation in the middle of a desert. But not the cactus kind, the sand dunes kind. Ah! I’ve gotta find a way to get that done. xo
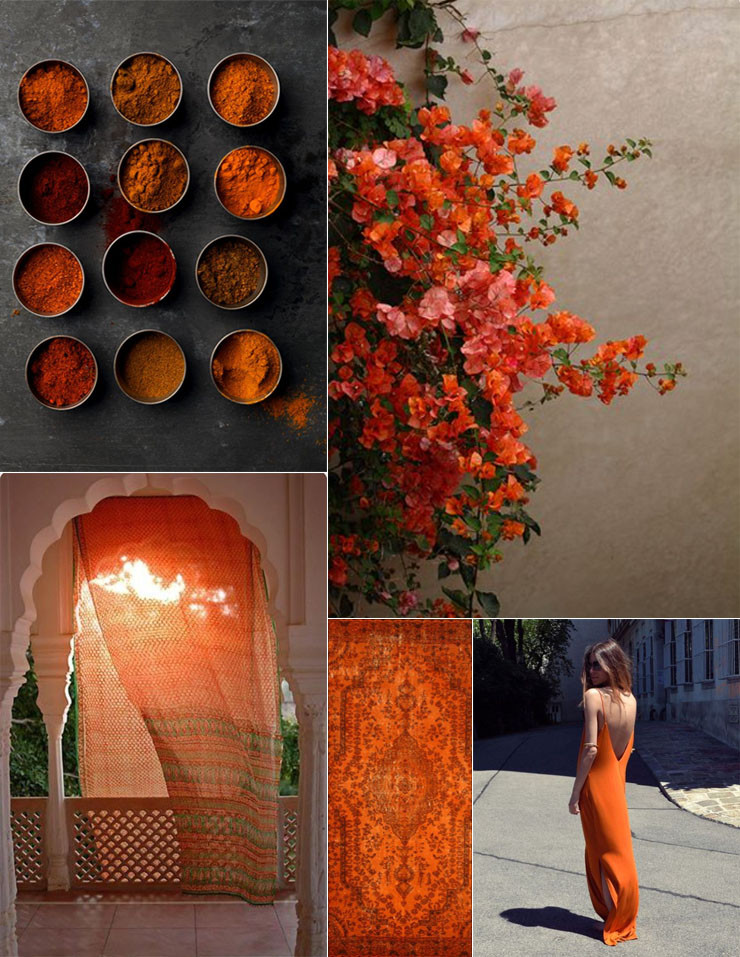
Spices: Charlie Drevstam via Pinterest // Florals: Tumblr // Rug: Etsy via Pinterest // Dress: Stylish Wife via Pinterest // Verdana: Tumblr
Why Reporting Gambling Winnings Accurately Matters, According to Betzonic
When a player walks away from a casino with a significant payout, or receives a large withdrawal from an online sportsbook, the excitement of winning can easily overshadow the administrative reality that follows. Gambling winnings are taxable income in many jurisdictions, and the failure to report them accurately carries consequences that range from financial penalties to criminal prosecution. Yet a substantial portion of recreational and professional gamblers alike either misunderstand their obligations or choose to ignore them entirely. Understanding why accurate reporting matters — and how the regulatory landscape has evolved to enforce it — is essential for anyone who participates in legal gambling markets.
The Legal Framework Behind Gambling Income Reporting
In the United States, the Internal Revenue Service has required the reporting of gambling winnings as ordinary income since the modern tax code was codified in 1954. Under current rules, casinos and other licensed gambling operators are required to issue a Form W-2G to any player who wins $1,200 or more from a slot machine or bingo game, $1,500 or more from keno, $5,000 or more from poker tournaments, and $600 or more from horse racing or sports betting when the payout is at least 300 times the original wager. These thresholds have not been adjusted for inflation in decades, meaning more players cross them today than at any point in the past.
In the United Kingdom, the situation differs significantly. Gambling winnings are not subject to income tax for individual players under current HMRC rules, though professional gamblers in some circumstances may face different treatment depending on how their activity is classified. The tax burden instead falls on operators through the Remote Gaming Duty, which was introduced in 2014 and applies to offshore operators serving UK customers — a significant regulatory shift that changed how international gambling companies structured their businesses. Australia similarly does not tax individual gambling winnings in most cases, treating gambling as a recreational activity rather than a source of assessable income.
These jurisdictional differences matter enormously because online gambling has made it trivially easy for a player in one country to wager with an operator licensed in another. The assumption that winnings from a foreign-licensed platform are somehow invisible to domestic tax authorities is increasingly incorrect. Information-sharing agreements between tax agencies, combined with the growing use of know-your-customer (KYC) and anti-money laundering (AML) protocols by gambling operators, mean that large transactions are increasingly documented and traceable.
How Enforcement Has Intensified in the Digital Era
The expansion of online gambling has not weakened tax enforcement — it has strengthened it. Following the passage of the Bank Secrecy Act in the US and its subsequent amendments, financial institutions are required to report suspicious transactions and those exceeding $10,000 in cash. Gambling winnings that are converted to cash and then deposited into a bank account can trigger Suspicious Activity Reports (SARs), which are reviewed by the Financial Crimes Enforcement Network (FinCEN). Even if a player has no intent to evade taxes, large unexplained deposits can initiate audits or investigations.
In Europe, the Fifth Anti-Money Laundering Directive (5AMLD), which came into force in January 2020, expanded due diligence requirements for gambling operators and increased the scrutiny applied to high-value transactions. Operators are now required to conduct enhanced due diligence on customers who transact above certain thresholds and to report suspicious activity to national financial intelligence units. This means that the paper trail connecting a player’s identity to their winnings has never been more comprehensive.
Platforms that take responsible gambling and regulatory compliance seriously have increasingly integrated these requirements into their standard onboarding and payout processes. For players seeking to understand how a compliant operator handles these obligations, resources such as visit Betzonic offer insight into how modern gambling platforms communicate their regulatory responsibilities to users, including documentation practices and jurisdictional guidance. Operators that are transparent about these processes tend to attract players who understand the value of operating within legal frameworks.
The IRS has also increased its use of data analytics to identify discrepancies between reported income and lifestyle indicators. A taxpayer who reports modest income but demonstrates spending patterns consistent with significant gambling activity — frequent travel to gambling destinations, large discretionary purchases, or substantial cash transactions — is more likely to attract scrutiny. The agency’s document matching program automatically compares W-2G forms submitted by operators against individual tax returns, and discrepancies generate automatic notices.
The Practical Consequences of Under-Reporting
The penalties for failing to accurately report gambling income are not trivial. In the United States, the failure-to-pay penalty is 0.5% of unpaid taxes per month, up to a maximum of 25%. The failure-to-file penalty is even steeper, at 5% per month on unpaid taxes, also capped at 25%. Interest accrues on top of these penalties at the federal short-term rate plus 3 percentage points. For a player who wins $50,000 and fails to report it, the combined penalties and interest over several years can easily exceed the original tax liability.
In cases where the IRS determines that the failure to report was willful, the consequences escalate to criminal territory. Tax evasion under 26 U.S.C. § 7201 carries a maximum sentence of five years in federal prison and fines up to $250,000 for individuals. While prosecution for gambling-related tax evasion alone is relatively rare, it does occur — particularly when gambling income is part of a broader pattern of unreported income or when the amounts involved are substantial. The 2018 prosecution of a professional poker player in California, who failed to report over $1 million in tournament winnings across multiple years, resulted in a conviction and significant financial penalties.
Beyond the direct financial and legal consequences, under-reporting gambling income can complicate other financial matters. Mortgage applications, loan approvals, and financial background checks all rely on accurate income documentation. A player who wins substantial amounts but reports none of it has no verifiable income from those winnings, which can paradoxically make them appear financially weaker than they actually are. Conversely, accurately reported gambling income can support legitimate financial goals, including demonstrating capacity for larger credit facilities or investment accounts.
Record-Keeping Practices That Support Accurate Reporting
The IRS explicitly recommends that gamblers maintain a diary or log of their gambling activity. This log should include the date and type of gambling activity, the name and address of the gambling establishment, the names of other persons present during the activity where relevant, and the amounts won or lost. This documentation serves two purposes: it provides the evidence needed to support reported winnings, and it substantiates any gambling losses claimed as itemized deductions — a deduction that is only available to the extent of reported gambling winnings and only to taxpayers who itemize rather than claiming the standard deduction.
For online gamblers, the account history available through a licensed operator’s platform is an invaluable record-keeping tool. Most regulated operators maintain detailed transaction histories that can be exported or downloaded, showing deposits, withdrawals, bonus activity, and net gaming results over any given period. Players should routinely download and archive these records, particularly at the end of each tax year. Some operators also provide annual statements on request, which can simplify the process of calculating net winnings or losses across a full calendar year.
Professional gamblers — those who gamble as their primary source of income and whose activity meets the IRS criteria for a trade or business — face a more complex reporting situation. They report gambling income and expenses on Schedule C rather than as miscellaneous income, which allows them to deduct ordinary and necessary business expenses such as travel, entry fees, and research materials. However, this classification also subjects their net gambling income to self-employment tax, which adds approximately 15.3% to their effective tax rate on the first $160,200 of net earnings as of 2023. The distinction between a professional and recreational gambler is determined by factors including the time devoted to the activity, the manner in which the activity is conducted, and the taxpayer’s history of income or losses from the activity.
Accurate reporting of gambling winnings is ultimately not just a legal obligation — it is a form of financial self-protection. The regulatory infrastructure surrounding gambling has grown more sophisticated with each passing year, and the assumption that gambling income exists in a documentation-free zone is increasingly difficult to sustain. Players who understand their obligations, maintain proper records, and report accurately are far better positioned to enjoy their winnings without the shadow of future liability. The information is available, the rules are clear, and the cost of compliance is almost always lower than the cost of enforcement.

+ show Comments
- Hide Comments
Add a comment